
What’s the biggest payment you make every month? If you’re a renter, it’s probably your rent.
But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It’s pretty frustrating, especially if you’d like to buy a home someday and you’re trying to build your credit.
The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.
The Problem for Would-Be Buyers
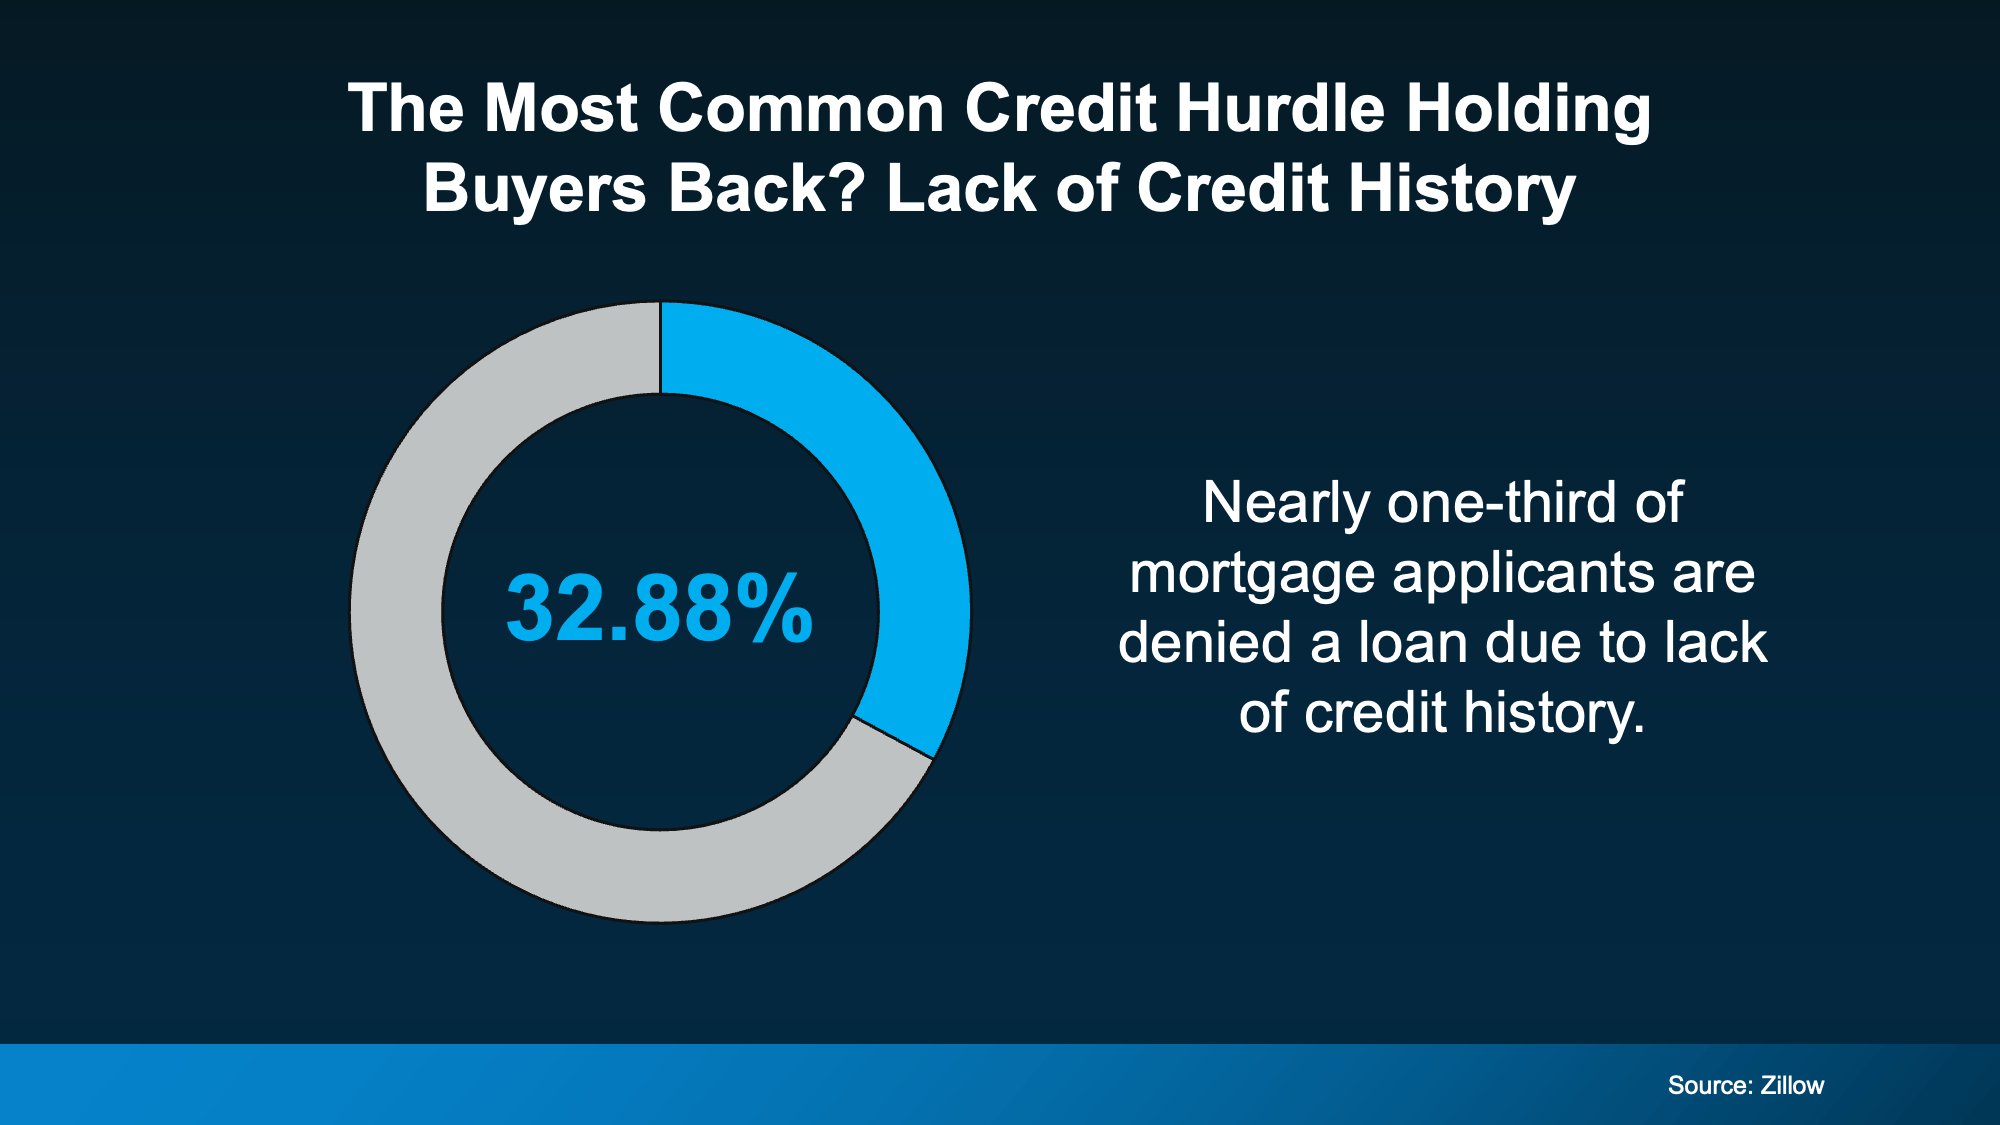
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history – not missed payments or too much debt. Just not enough credit history for a lender to say “yes.”
It’s the most common hurdle would-be buyers have. As Zillow explains:
“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”
But there’s finally a way in now that how credit gets measured is changing.
The Good News: Credit Is Getting Broader
As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:
“Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”
Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.
VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.
A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.
Here’s the catch though, you still have to walk through it.
Counting Rental Payment History Is Not Automatic
There are more options available to build credit, but you have to be proactive. Your rent won’t necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.
Here’s how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:
-
Ask your landlord or property manager if your rent is being reported. If it’s not, opt in.
-
If your landlord doesn’t offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.
-
Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.
-
Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don’t apply for a bunch of new credit at once.
-
Don’t close any accounts – even if you have paid them off and don’t use them often.
-
Diversify your profile by getting a secured credit card or becoming an authorized user on someone else’s account to help you build history beyond rent.
These steps take a little time and effort, but it could be worth it if it starts building up your credit history.
Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better.
Even if you’re not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.
Bottom Line
The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.
Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you’re closer to owning a home than you think.




